Apollo conversation
How do venture capital investors identify winning AI companies when everyone is an AI company?
The conversation
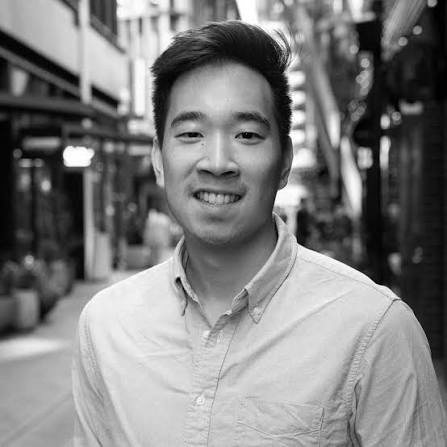
How do venture capital investors identify winning AI companies when everyone is an AI company? You take AI as part of the base stack, do your due diligence and apply the same SaaS fundamentals that are used to assess a pre-revenue company. That was my takeaway from my conversation with Nick Ooi, Investment Manager at Investible.
Nick began his career in management consulting, working with large ASX-listed corporations and private equity firms looking to acquire growth-stage, tech-enabled businesses. His interest in technology went further back, though. While studying law and commerce at university, he built multiple social enterprise businesses with friends. After a few years in consulting, Nick began to consider a life where he could work closer to technology and utilise his consulting experience. Having now spent over five years in venture capital, I was excited to talk to him about what he finds important in founders and investments.
One of the first things Nick said to me was that having a love for tech was the baseline:
“You have to love tech, like regardless, and tech and particularly start-ups, ’cause that is what you’re doing on a day-to-day basis.”
One of the reasons I wanted to speak with Nick was that, as an Investment Manager, I knew his days were going to be filled with meeting founders, evaluating decks, hunting the next unicorn, etc. But I’ve been wondering for months: in an age where you can build a start-up in three days with AI and the Lovables of the world, where Anthropic reportedly sees a potential market of more than $30 trillion and everything seems to be moving at 2,000 miles an hour, how on earth do you find a company worth investing in?
Enter my conversation with Nick.
First, I wanted to understand what makes a successful investor. Venture is governed by power laws, a relatively small number of investments can drive the majority of a fund’s returns. So what does a good investor look like?
The baseline - a love or obsession for technology, problem-solving and the start-up ecosystem - makes sense. The more interesting skill Nick pointed out was “learning how to read people.”
VCs are constantly assessing founders, particularly at the early stage when metrics might not be mature or exist at all. To an extent, you’re betting on a person: the founder.
It’s important to understand their motivations. Why is someone willing to spend 10 years working on an idea that will probably fail? On an idea that is, frankly, pretty crazy to pursue? Does this person have enough belief and conviction to outlast the 101 reasons why they might fail?
That’s what the investor is looking to buy into.
We moved into founders next. I wanted to understand the how, who and what, from the initial meeting onwards.
When an idea comes across Nick’s desk or into his inbox and piques his interest, he usually kicks off proceedings with a simple introduction, often a coffee catch-up. Although it may seem and feel like a casual, friendly conversation, the potential investor is already reading, assessing and forming a view of the founder.
Nick prefers meeting in person where possible. The world is more connected than ever, but there’s still something about sitting face-to-face with someone when you’re trying to understand who they are.
One of the key things Nick tries to understand when meeting new founders is the why . Why is this person trying to tackle this problem? Have they worked in the field already? Are they domain experts?
VCs like to call this Founder-Market Fit. As Nick explained:
“Do they have the unique insights into being able to solve that particular problem that they’re tackling? Maybe they’ve spent decades within an industry where it’s a very niche problem that no one else has experienced, or maybe they have some unique insight into solving that problem that no one else does. So, why they’re the right person, why the right team to win in this market.”
I thought this was a really concise, efficient way of thinking about it. It cuts through a lot of the bells and whistles and answers one of the key questions VCs are looking to answer: why are you the right person or team to build this?
There are also the more formal decks and accompanying materials, but for funds looking at pre-seed and early-stage start-ups, there isn’t always a huge amount of quantitative information available. Before the polished Gamma deck becomes the focus, the investor needs to understand whether the business can scale, whether they believe in the founders and whether the problem is worth solving.
In the absence of revenue, the team at Investible like to really drill into the market the company is operating in. Where there may be a lack of customers, they can leverage their network to understand who the potential customers might be, whether they would pay for a solution like this and what they’re already using to solve the problem.
Customers and users are still fundamental to understanding product-market fit. Speaking to users is valuable even if they’re not paying customers. How sticky is the product? How often are they using it? Daily, weekly, monthly? Competitors in the space can also give an understanding of the market and appetite for the product.
Even without much revenue data, there’s still a lot to investigate.
We spoke about the overall founder/investor fit, and Nick made it clear that investors need to understand the motivations of the person trying to solve the problem. Commitment is a huge part of it.
If a founder is working part-time on the company or juggling multiple ventures, it isn’t necessarily a red flag, but the investor wants to understand why. As Nick put it:
“We want you to be 100% all in on the venture you’re building because that’s what we’re backing.”
Having the right team is essential too. Sole founders are absolutely investible, but Nick pointed out that they need enough self-awareness to recognise their weaknesses and bring in people who can complement their existing skill set.
When we discussed this more, it made quite a lot of sense. More complementary skills, more capability. Building alone is simply harder.
So say you’ve found the next unicorn. You’re convinced, you’ve convinced the team and you want to invest. Assuming you’re one in a long line of well-funded, well-connected national and international venture firms with chequebooks at the ready, how do you convince the company that you’re right for them?
Surprisingly, Nick spoke about how collaborative the Australian venture ecosystem is, at least in his experience. Investible has co-invested with firms across the country, with funds often aiming to win together. A far cry from the usual cut-throat nature of the investment world one might expect.
When a situation arises where there isn’t enough room for every interested VC, Investible leaves it to the founders to decide who they want around the table.
The question of how you pick the right fund is one I’ll need to save for a founder conversation.
What is important is that funds offer the right things. Capital, of course. Beyond that, there might be industry-specific expertise, networks or international market access. What a company needs at a particular point in time will determine the right investor.
And ultimately, it’s a relationship.
“Venture capital is a relationship game, so founders need to pick VCs that they are willing to work with as people.”
Nick and Investible like to work on trust. They partner with companies that can trust them to advise and collaborate, and, as Nick put it, “roll up their sleeves and help you out” through both the highs and the lows. They can remain hands-off when needed, but only a phone call away when they’re not.
I was curious as to how the Australian venture capital landscape became so collaborative. I always assumed that, in this high-stakes game of life poker, it would be a dog-eat-dog world.
Nick explained that there are more VC firms emerging and more capital flowing into Australian start-ups, which is ultimately good for the ecosystem. Where things do become competitive is around those higher-conviction plays: second or third-time founders, businesses operating in very large markets and companies with the potential to shoot the moon in terms of growth.
Those deals, like anywhere, remain extremely competitive.
We moved to AI, again. I wanted to know how it has changed who Nick speaks to and what he focuses on over the last 12–24 months.
AI has become table stakes at this stage, with around 80–90% of the companies pitching to Investible being AI-native. Investible no longer necessarily sees AI as an edge in itself. As Nick put it:
“Traditional software is now AI-native. If you’re leveraging AI in your software platform, that’s sort of table stakes now.”
But it does raise the question of defensibility. Just like traditional SaaS: how defensible is your platform in the long term?
Particularly when you have the model providers themselves moving further into the application space. Could an OpenAI, Anthropic or Google build its own vertical solution and disrupt an entire category of young start-ups? Nobody knows, but it’s another consideration when assessing defensibility in today’s market.
Overall, though, Nick’s feeling is positive. He described it as a fascinating time to be investing because of the new technology, infrastructure and applications emerging.
As we can all build and deploy quicker than ever, does that create more noise? Can you see through it and find the gems?
Nick is already seeing companies reach significant ARR with only a couple of founders and a handful of employees. The question then becomes less about whether that early growth is possible and more about whether it can last.
Enterprise AI adoption, in reality, is still relatively experimental. Companies might sign up for a month-long trial or even a year-long contract to test a product. Why wouldn’t they? There’s so much on the market that organisations can run products simultaneously and see which offers the best solution.
The real question comes afterwards: do they stay?
Nick pointed to companies in the US that grew incredibly quickly in their first one or two years, only to see revenues decline where the product wasn’t durable enough or lacked a genuine moat.
So where are the really defensible companies? What makes them truly defensible?
This is where Nick believes the SaaS traditions are still relevant. Proprietary data. Network effects. The quality of your customers. Are those customers inherently sticky?
And ultimately, product-market fit. Do customers pay for it? Are they willing to stick around?
There are nuances around the business model itself - margins, token usage and, of course, unit economics - but, as Nick put it:
“The fundamentals are still relatively the same.”
Turns out it still takes a lot to make a company successful, even with all the technological advances.
What about Australia? Where can Australia gain an advantage over Silicon Valley, Stockholm or Europe In general? Where can Australia build genuinely globally important technology?
Probably the multi billion-dollar question.
Nick thinks it will come from what Australia is already good at, which is quite reflective of the wider economy. Mining has been around for decades and remains a major driver of GDP. Services are also a huge part of the Australian economy.
The opportunity is in applications that can address problems inherent in these industries. One of Nick’s observations that I found particularly interesting was that AI companies are increasingly “tackling more of the labour spend than the software spend.”
Agentic solutions can streamline workflows, but more importantly, they can increasingly deliver the outcome itself. Instead of a human logging into a SaaS platform and completing the workflow, the technology can begin to complete the task.
People ultimately care about the outcome.
Infrastructure is another area we’re seeing and reading about more often. Data centres are exploding, with the pipeline jumping from 97 to 225 projects In Australia, according to recent energy market data.
Nick also pointed towards model capability and sovereign models. There are already companies working in this space, but having genuine domestic model capability could make Australia more relevant in the AI race and reduce reliance on technology developed entirely overseas.
I wanted to ask about Investible’s successful investments, and luckily for me they had just announced a recent milestone with portfolio company Apate.ai, which raised $11.4 million to fuel expansion into the UK and US.
Nick called it a fascinating business. It uses AI to build a conversational army of bots that pretend to be consumers and engage scammers, wasting their time.
More importantly, the technology extracts relevant intelligence around the financial details and personal information these scammers are targeting, then surfaces that information to the banks and financial institutions those consumers use — effectively helping prevent scams before they happen.
Pretty smart, huh?
It’s a fascinating use of AI in an otherwise unsexy business, built around solving a very real problem.
They’ve already got Commonwealth Bank on board, alongside other large Australian financial institutions. Investible has been backing Apate.ai since it was pre-revenue, with no customers.
They bought into the founders and what was unique about their skill sets and solution, while recognising the sheer size of the problem they were tackling. Scam prevention isn’t an Australian problem; it’s a global one, and financial institutions face both regulatory and financial consequences when they fail to protect customers.
Brilliant to hear about a company from Australia succeeding in the local market and now expanding across the ponds; great to see Investible in the game early too.
My final question to Nick was: as Apate.ai looks to expand internationally, what advice would he give founders? What do companies most often underestimate when expanding internationally? What are the biggest challenges?
Customers. Sales motions. Expansion. All those glorious challenges that come with growth.
“You’re basically starting from scratch.”
Identifying prospects is part of the challenge, but that comes alongside different buying habits, regulatory regimes, sales cycles and appetites for products.
Then there are the people. Building a sales function in a foreign market from scratch can be really hard, and those first one or two hires can be critical. Nick has seen companies expand from Australia into markets like the US only to discover small but important differences in how customers buy.
Get those initial hires wrong and, according to Nick, it can stall a company’s progress for six to twelve months .
As with most young companies, time is never a friend. When you’re operating on a finite runway, losing six to twelve months can be enormous.
Closing out our conversation, I had to ask Nick one final question: if he could advise founders raising their first round, what’s the golden nugget?
His answer was simple:
“I would say come prepared.”
Know why you’re raising in the first place, how much you’re looking to raise and what you’re going to use the funds for.
Nick speaks to founders who haven’t fully answered those questions yet. His view is that preparation makes the entire process easier: have your materials ready, have your data room in order and understand your customers and financials.
The founders who are most prepared can usually run a more structured process and close their rounds quicker. Those figuring it out on the fly risk spending months pulling a round together, eating into runway and distracting themselves from actually selling.
Raising for the sake of raising won’t cut it. The companies best positioned to raise are clear on why they need the capital and what they’re going to do with it.
I really valued my conversation with Nick. He shone a surprisingly bright light on the Australian technology ecosystem. I pondered problems that could be solved and big markets for the entire weekend after.
Although I think I’ll leave the scam robots to the experts.
Apollo Insight is a series of conversations with the founders, investors and operators building technology companies.
If you enjoyed this conversation, subscribe to Apollo Insight for the next one.
Apollo Insight · Website · LinkedIn · X